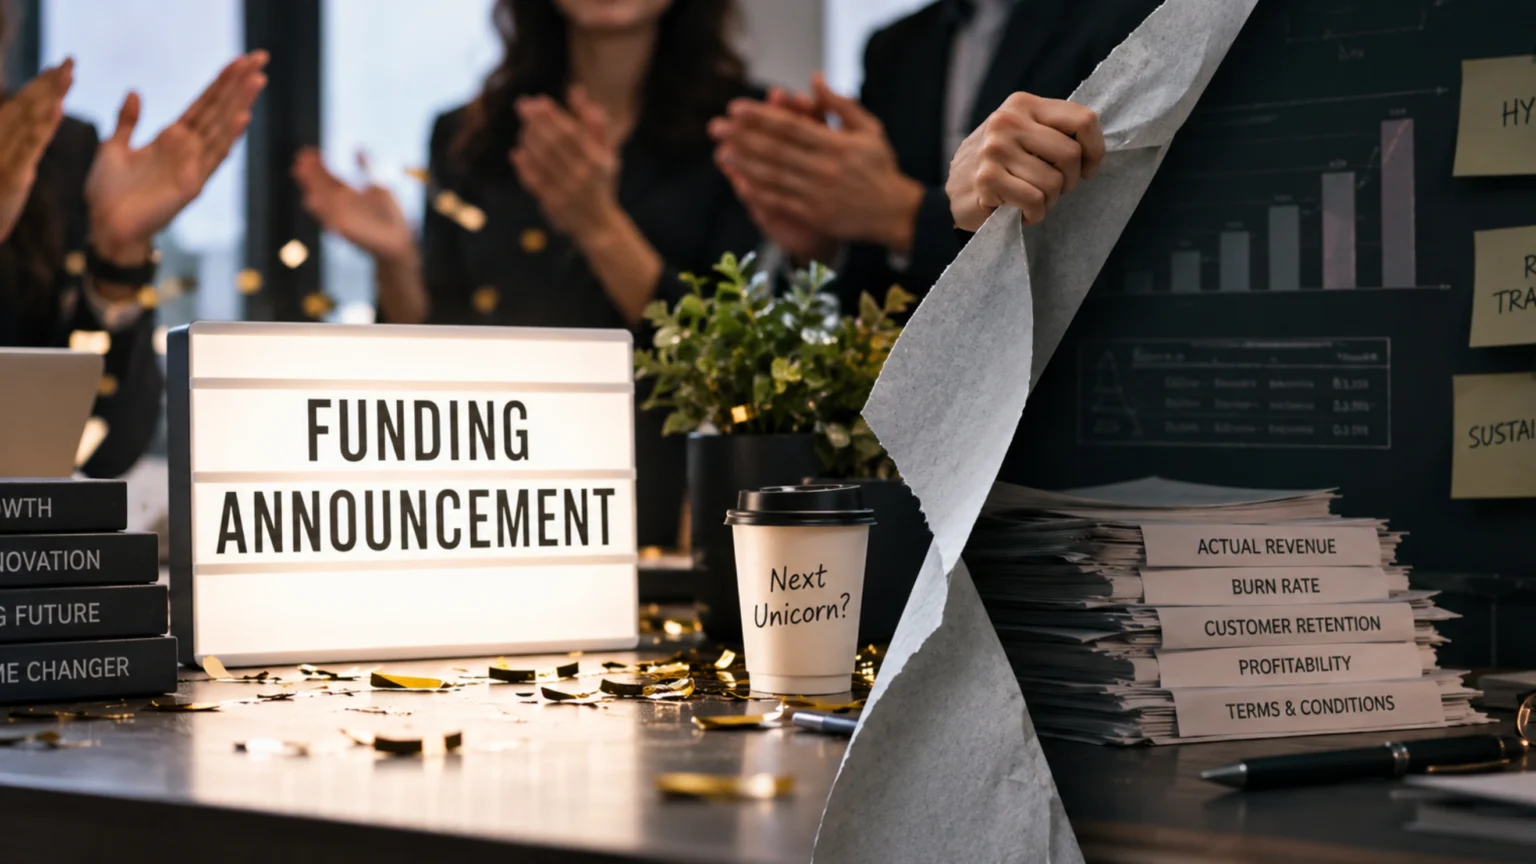

The headline value of a funding round often reveals little about its underlying financial significance. The announced amount may include secondary share purchases, undrawn credit facilities, and capital tied to future conditions, while preferential investor rights can materially alter the transaction’s economic value.
When a start-up announces a $100 million financing, markets tend to interpret the figure as a direct addition to its balance sheet. The reported valuation quickly becomes a benchmark for growth, investor confidence, and sector momentum. Yet the announcement alone rarely establishes how much fresh capital the company has received, what obligations accompany it, or how the transaction has changed ownership and control. The arithmetic looks straightforward, but it rarely is.
The announced $100 million may not represent an equivalent increase in the company’s cash reserves. It could include debt, secondary share purchases, or capital committed for later closings. The reported valuation may also apply to preferred shares carrying protections unavailable to employees and ordinary shareholders.
That does not make the announcement inaccurate, but it limits what investors can infer from the headline. A funding release states the size of a transaction; it does not disclose the company’s complete financial position.
This has become more significant as venture capital moves towards fewer, larger deals. KPMG estimated that global venture investment exceeded $500 billion in 2025, up from $391.9 billion in 2024, even as deal activity declined sharply. Much of the increase came from a relatively small number of megadeals.
Such transactions can raise aggregate funding totals without improving access to capital across the wider start-up market. Likewise, the announced size of a round does not reveal how much usable capital entered the company or how far it extended its financial runway.
Who receives the money?
The financial significance of a funding round depends less on its headline size than on where the capital ultimately goes.
In a primary financing, investors subscribe to newly issued shares and the proceeds enter the company. That capital can fund recruitment, product development, market expansion, acquisitions, or working-capital requirements. The trade-off is dilution: because the company issues additional shares, the percentage ownership of existing shareholders declines.
A secondary transaction has a different economic purpose. Investors purchase shares from founders, employees, or early financial backers. The ownership changes hands, and the sellers gain liquidity, but no fresh operating capital enters the company.
Late-stage funding rounds increasingly combine the two. A company may announce a $250 million transaction comprising $150 million in primary capital and $100 million in secondary share purchases. The full figure accurately reflects the size of the deal, but only $150 million strengthens the company’s cash position. Treating the entire amount as fresh funding would overstate the effect on its balance sheet and financial runway.
Secondary sales are not, by themselves, a sign of weakness. They allow employees to realise part of the value accumulated through years of equity compensation. Founders can reduce their personal financial concentration without relinquishing control, while early venture investors can return capital to their limited partners when an acquisition or public listing takes longer than expected.
For market participants, however, shareholder liquidity and corporate financing are not equivalent. One transfers value between owners; the other provides capital that the business can deploy.
Stripe’s 2023 Series I financing illustrated the difference. The payments company announced a transaction of more than $6.5 billion at a $50 billion valuation. The proceeds were intended to provide liquidity to current and former employees and meet tax obligations associated with equity awards. Stripe explicitly stated that it did not require the capital to finance its operations.
The deal was substantial in size and important for employee liquidity, but it did not represent a conventional growth-capital raise. Its headline value measured the scale of the transaction, not the amount of new money available for business expansion.
Equity, debt and the advantage of one large number
Funding packages increasingly combine several forms of capital. Publicity tends to compress them into one figure.
A $120 million announcement could consist of $50 million in new equity and a $70 million debt facility. Equity is permanent capital in the conventional sense; debt must be serviced and repaid. The facility may also be only partly available when announced.
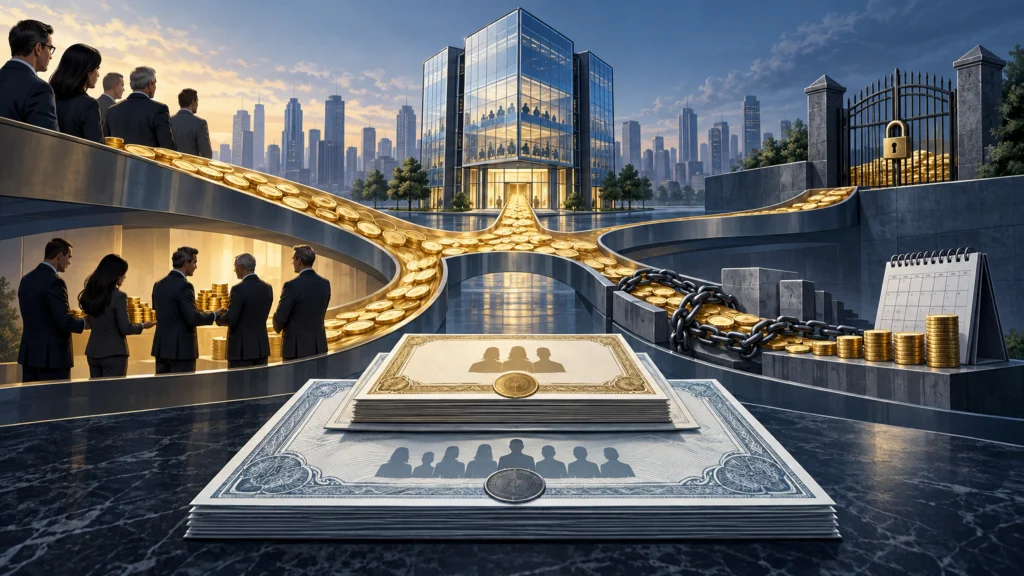
A lender might approve a maximum borrowing limit while releasing the money in stages. Further drawings can depend on revenue, cash reserves, investor support or other agreed targets. The company can therefore announce access to $70 million without having borrowed—or received—the entire amount.
Debt is not inferior to equity. For a company with predictable revenue, it may finance expansion without forcing founders and existing investors to surrender another large share of ownership. Used carelessly, however, it can intensify financial pressure. Interest consumes cash. Repayment dates arrive whether or not growth targets have been met. Covenants may restrict acquisitions, additional borrowing, or spending. Some venture loans include warrants that give lenders the right to acquire shares, adding a measure of future dilution.
The hierarchy becomes especially important when a company is sold under difficult circumstances. Lenders are paid before shareholders. Preferred investors may then receive their contractual entitlement, leaving ordinary shareholders to divide whatever remains.
Convertible notes occupy the ground between debt and equity. They generally begin as loans and later convert into shares, often at a discount or under a valuation cap. The company receives money when the note is issued, while the ownership consequences emerge later.
SAFEs defer that calculation differently. The US Securities and Exchange Commission describes a SAFE as an agreement promising a future ownership interest once a specified event, such as an equity financing or acquisition, occurs. Until that event, the holder does not yet own the resulting equity.
A business that has issued several SAFEs may appear to have a relatively simple cap table. When those instruments convert, the dilution can be considerably larger than founders or smaller shareholders expected.
A commitment is not cash in the bank
Funding language is often read with more certainty than it deserves.
“Closed” usually indicates that legal completion has occurred. “Committed” suggests that an investor has agreed to provide capital, though payment may come later.
“Secured” can describe signed financing, a credit facility, or even an agreement that remains subject to closing conditions. A company “seeking” or “in talks to raise” money has not completed a round at all.
Large financings are also divided into tranches. Investors release an initial amount and hold back the remainder until the company satisfies agreed requirements.
OpenAI’s $40 billion SoftBank-led financing in 2025 offered a prominent example. The transaction was structured around an initial $10 billion, with as much as $30 billion expected later.
The full investment was tied to conditions surrounding OpenAI’s corporate restructuring, and SoftBank could reduce its contribution if those requirements were not completed.
Reporting the round at $40 billion reflected its proposed maximum size. It did not mean the entire amount reached the company when the announcement was made.
Conditions attached to later tranches can include regulatory clearance, corporate reorganisation, revenue thresholds or participation from other investors. They are not procedural footnotes. They determine whether the company receives the money on which its expansion plans may depend.
A term sheet deserves similar caution. It records the broad commercial understanding among the parties but may leave much of the proposed transaction non-binding. Due diligence, final agreements and regulatory requirements still stand between an agreed term sheet and a completed investment.
The practical questions are less glamorous than the headline: How much has closed? How much has been transferred? What remains conditional? When can the company use it?
The valuation may describe the security, not the whole company
A private-market valuation is a negotiated outcome. It is not an independent appraisal of every share already in existence.
Confusion often begins with the difference between pre-money and post-money valuation. If an investor places $20 million into a business valued at $80 million before the round, the post-money valuation becomes $100 million, and the investor owns 20 per cent.
If the stated $80 million is a post-money valuation, however, the same investment buys 25 per cent. The SEC notes that the choice between pre-money and post-money valuation can have a significant effect on ownership percentages.
The share class matters just as much. Institutional investors usually receive preferred shares. Those securities may include liquidation preferences, anti-dilution protection, board rights, access to information, and approval rights over important corporate decisions.
A one-time liquidation preference commonly allows an investor to recover the original investment before ordinary shareholders receive proceeds. Other structures can offer more generous protection. If a company raises money at a $1 billion valuation and is later sold for substantially less, the contractual order of payment may matter far more than the valuation attached to the previous round.
Employees typically hold ordinary shares or options. Founders may also own ordinary shares. Assigning them the same economic value as newly issued preferred shares can therefore exaggerate what those holdings would produce in a sale.
Private valuations also suffer from limited price discovery. A relatively small investment at a high share price can establish a large headline valuation even though only a fraction of the company has been tested in the transaction. Unlike a listed share price, it is not being continuously challenged by a broad market of buyers and sellers.
The valuation tells investors the price accepted in a particular deal. To understand what that price means, they need the rights attached to the security and the assumptions built into the transaction.
Dilution rarely stops at the round itself
A press release may state that new investors have acquired 20 per cent of the company. Existing shareholders can still lose more than 20 per cent of their ownership.
Before completing a round, investors frequently ask the company to enlarge its employee option pool. If that expansion occurs before the financing, the resulting dilution is borne by the existing shareholders. The new investor then purchases the agreed percentage from a larger pool of shares.
Convertible notes, SAFEs and warrants can convert at the same closing. Each claims another portion of the company. Public announcements seldom provide a fully diluted ownership table showing the combined effect.
Carta’s analysis of software start-ups found that median primary dilution remained close to 20 per cent at both the seed and Series A stages in 2024. It also found that bridge and extension rounds could impose additional dilution equivalent to roughly half that of the original primary round. A company that sells 20 per cent in a seed round and another 10 per cent in an extension has given up considerably more ownership than either announcement suggests on its own.
Dilution is not automatically destructive. A smaller stake in a well-capitalised, growing company may become more valuable than a larger stake in a business unable to finance its plans. The proper test is whether the money raised is likely to create more value than the ownership surrendered. That judgment cannot be made from the valuation alone.
Filings provide a firmer record
Private companies disclose far less than listed businesses, leaving much of the interpretation to journalists, databases and company statements.
In India, a company allotting securities through a private placement must file a return of allotment with the Registrar of Companies through Form PAS-3. The filing records the securities issued and provides firmer evidence that an allotment has taken place. Under the current filing framework, the return for a private placement is generally due within 15 days of allotment.
The filing will not necessarily disclose every side agreement, investor protection or debt covenant. It may also appear after the first reports have circulated. Even so, it can help separate an intended financing from securities that have actually been allotted.
Investors examining startup funding announcements should reconstruct the transaction rather than simply repeat its largest number. They need to know how much primary capital entered the company, what portion went to selling shareholders, whether debt was included, and how much remains undrawn. They should establish whether the round has closed, identify the conditions attached to later payments, and determine whether the reported valuation is pre-money or post-money.
The rights attached to the new shares deserve equal attention. So do the enlarged option pool, outstanding convertible instruments and the company’s rate of spending.
A $100 million primary investment may provide little comfort if the company is losing $20 million every month. A smaller round could transform the prospects of a disciplined business with modest cash requirements. Funding size without expenditure tells investors almost nothing about runway.
Startup funding announcements still provide useful information. They show where investors are placing capital, establish reference prices, and can signal confidence in a company’s prospects. They simply do not provide enough information to support the conclusions routinely drawn from them.
The announcement is the public version of the transaction. The investment case lies in what it leaves out.
Stay connected with Business Herald for the latest business news, insights, and updates.
Follow us on Facebook, Instagram, LinkedIn, and YouTube.
Join our growing community on WhatsApp and Telegram for real-time updates delivered directly to you.